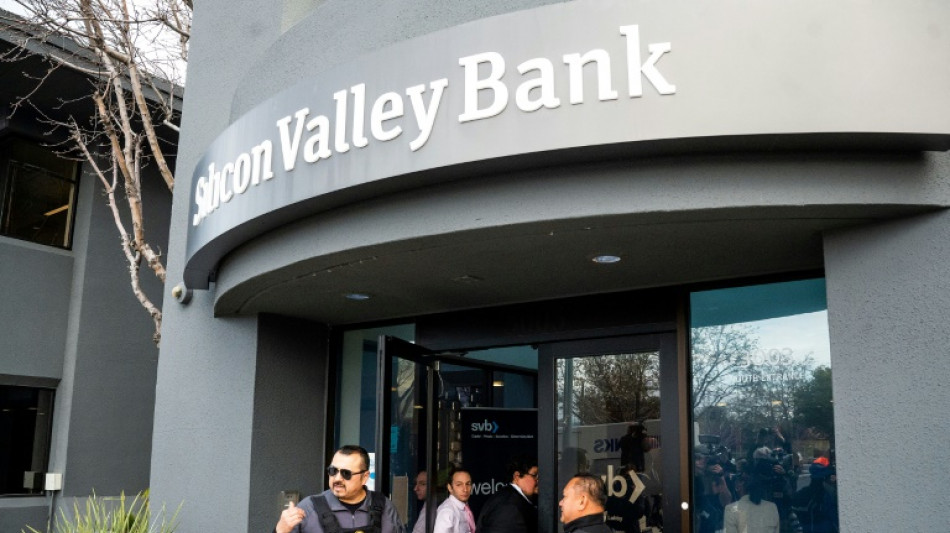
SVB's demise: Why didn't US bank regulators see it coming? / Photo: NOAH BERGER - AFP

With hindsight, there were warning signs ahead of last week's spectacular collapse of Silicon Valley Bank, missed not only by investors, but by bank regulators.
Just why the oversight failed remained a hot question among banking experts Monday, with some focusing on the weakness of US rules.
The Federal Reserve announced Monday plans for a "thorough, transparent and swift" review of the supervision of SVB that will be publicly released on May 1, effectively acknowledging that it could have done better.
President Joe Biden promised a "full accounting of what happened," adding that he would ask regulators and banking regulators to tighten rules on the sector.
Banking experts have been among those alarmed at the rapid collapse of SVB, the country's 16th biggest bank by assets and how its demise became a harbinger of Sunday's failure of another lender, Signature Bank.
The failures have "exposed the inadequacy of regulatory reforms that have been made since the global financial crisis," said Arthur Wilmarth, a law professor at George Washington University.
A once-over of the bank would have pointed to clear potential red flags in SVB's disproportionate exposure to tech startups, a risky area that can be likened to commercial real estate or emerging markets -- areas that have plagued lenders in the past.
Wilmarth noted that SVB grew very fast between 2020 and 2022 and that its exposure to long-date fixed interest bonds made it especially vulnerable to the a shift in monetary policy by the Fed.
"That's almost a sure proof formula for failure. If the economy turns you begin to have trouble," Wilmarth said.
"None of those would have been a mystery to the regulators."
- No excuses -
Experts pointed as well to the eventual easing of US laws enacted soon after the 2008 crisis.
The original Dodd-Frank law of 2010 imposed higher capital, liquidity and other requirements on banks with at least $50 billion in assets.
In 2018, with support from former President Donald Trump, this requirement was raised to $250 billion, affecting fewer banks.
But that shift in law does not excuse regulators for these failures, according to Anna Gelpern, a law professor at Georgetown University.
"When regulatory requirement are relaxed either by the premise that those institutions don't pose a risk to the system because of their size or that they are easier to supervise, that puts much more pressure on old-fashioned supervision because you don't have the automatic alarm that goes off with the requirements," she said.
"If this was clearly unsafe and unsound behavior," the banks' official designation in the law "does not excuse a failure of supervision," she said.
Michael Ohlrogge, an associate professor of law at New York University, said regulators as a matter of course assign "very little to zero-risk weight" in terms of bank capital requirements for Treasury-linked securities because they are considered safe.
At the same time, regulators are also lenient with banks with regard to depositors with more than $250,000 -- the threshold for federally insured deposits -- believing the bank has a meaningful business relationship with such clients.
"That's probably going to warrant revisiting and thinking more seriously about the run risk of uninsured deposits," Ohlrogge said.
T.Sato--JT